Brent Crude Drops 1.4% as Hormuz Reopening Signals Emerge
Oil fell to $98.83 per barrel Sept. 25 as investors bet on the strait reopening. What the decline means for diesel and small-fleet fuel bills.
Will the Strait of Hormuz reopen soon?
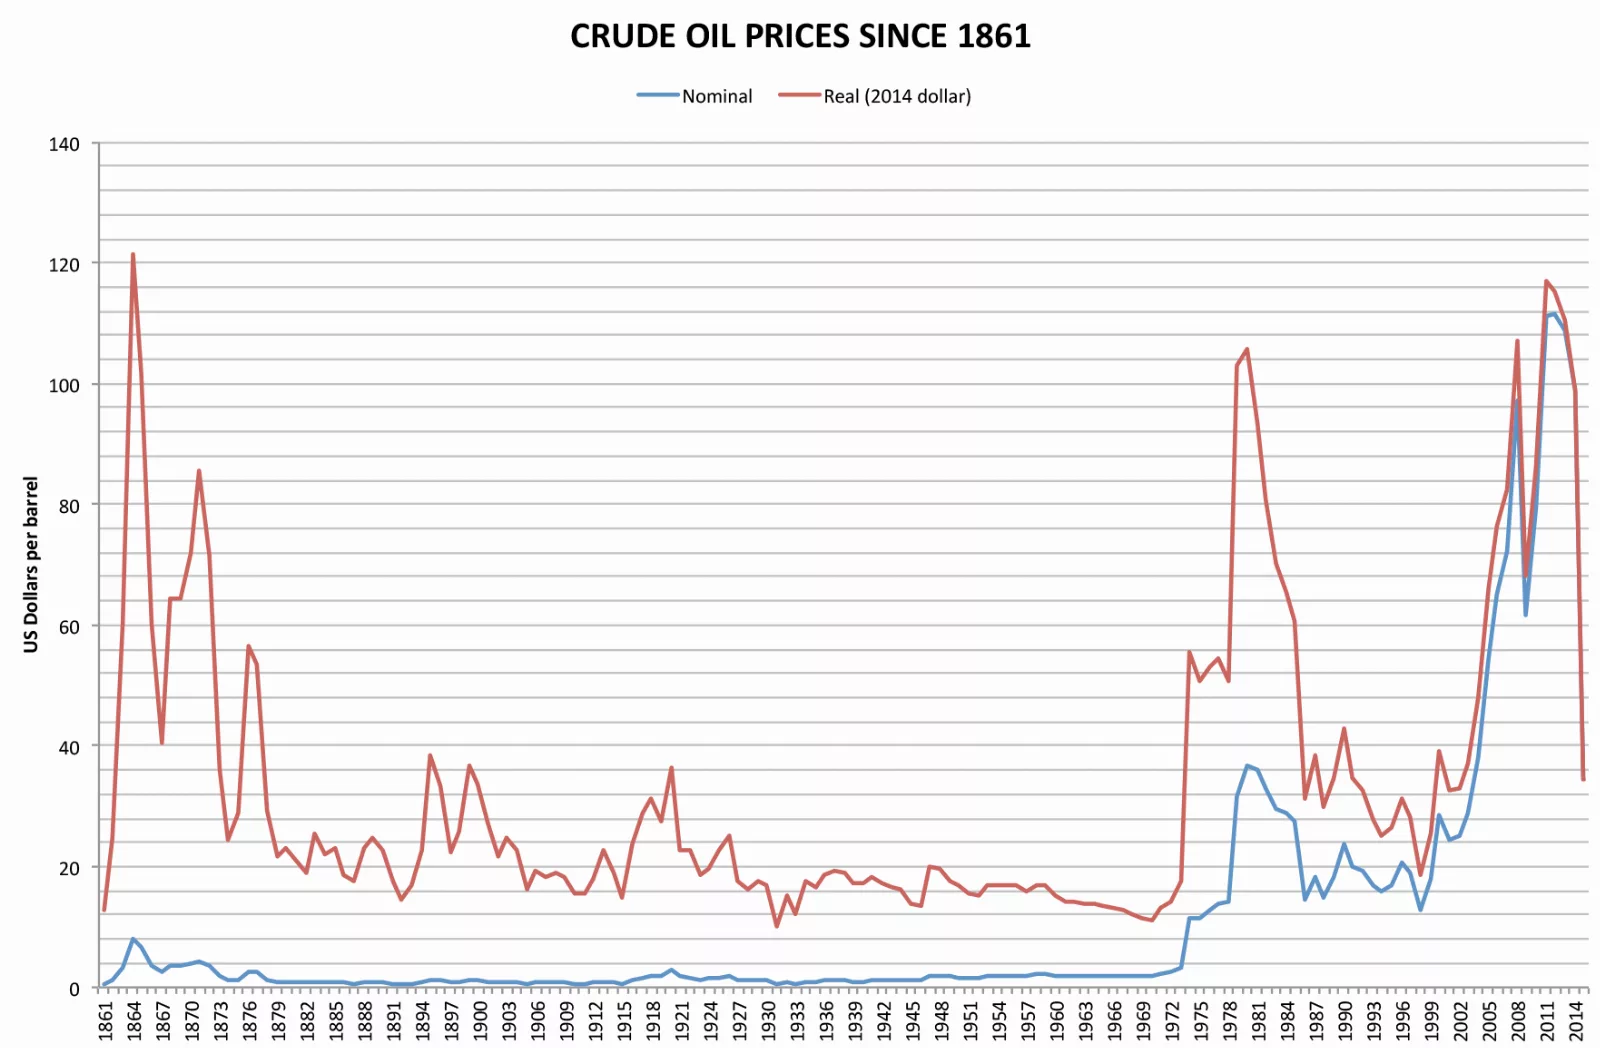
Brent crude dropped 1.4% to $98.83 per barrel Sept. 25 as investors looked for signs the Strait of Hormuz would reopen. The decline marks the first sustained retreat from the multi-week highs that followed the Iran conflict's escalation in July.
The strait has been partially closed or disrupted since mid-summer, choking off roughly 20% of global crude supply and sending diesel prices to multi-year highs. A full reopening would ease the supply crunch that has kept U.S. diesel elevated and forced small fleets to absorb fuel surcharges that rarely cover the full cost.
What the $98.83 price means for diesel
Crude at $98.83 per barrel translates to roughly $4.20 to $4.50 per gallon at the pump for diesel, depending on regional refining margins and state taxes. That is down from the $4.80 to $5.20 range fleets saw in early September when Brent touched $97.33, but still well above the $3.50 baseline most small carriers budget for.
Every 10-cent move in diesel costs a five-truck fleet running 100,000 miles per month an extra $1,500 in fuel expense, assuming 6 mpg average. A 50-truck operation running a million miles monthly sees $15,000 in added cost for the same dime. The Sept. 25 decline shaves roughly 30 cents off the peak, returning $4,500 per month to the five-truck fleet and $45,000 to the 50-truck operation if the drop holds through October settlements.
Why investors are betting on a reopening
The 1.4% decline signals that traders expect some resolution to the Hormuz disruption, though no official announcement of a reopening timeline has been made. Oil markets move on expectation as much as fact. A sustained drop below $95 per barrel would indicate that tanker traffic is resuming at pre-conflict volumes.
The strait normally carries 21 million barrels per day, roughly one-fifth of global crude supply. Even partial reopening would flood refineries with feedstock and ease the diesel supply crunch that has kept pump prices elevated since July. U.S. refineries hit their highest run rate since 2019 in August, processing 17.4 million barrels per day to meet demand, but they cannot refine crude they do not receive.
What small fleets should watch
The Sept. 25 price is a signal, not a settlement. Diesel lags crude by two to four weeks depending on regional refining schedules. If Brent holds below $100 through mid-October, expect pump prices to fall into the $4.00 to $4.30 range by November. If the strait remains closed or fighting escalates, crude could reverse and push diesel back toward the $5.00 threshold some analysts warned about in early September.
Small fleets should lock fuel at current rates if their lanes and margins allow it. A 10% decline in diesel from peak saves a 10-truck fleet running 200,000 miles per month roughly $6,000. That is the difference between breaking even and banking a profit on thin-margin contract freight. Spot rates have not moved enough to absorb the fuel swings, so the cost falls directly to the carrier.
The bill if Hormuz stays closed
If the strait does not reopen and crude climbs back above $100, diesel will follow. The $7 to $9 per gallon forecast some strategists issued in early September assumed prolonged closure and a complete halt to Middle East crude exports. That scenario has not materialized, but it remains possible if fighting intensifies or if Iran closes the strait entirely rather than allowing partial tanker passage.
At $7 per gallon, a five-truck fleet running 100,000 miles monthly would pay $116,667 in fuel, up from $58,333 at $3.50 per gallon. The difference is $58,334 per month, or $700,000 annualized. Most small fleets cannot pass that cost to shippers without losing the load to a larger carrier with better fuel hedging. The result is either parked trucks or negative margins on every dispatch.
The Sept. 25 decline buys time, but it does not erase the risk. Watch Brent. When it moves, diesel follows, and your settlement statement moves with it.